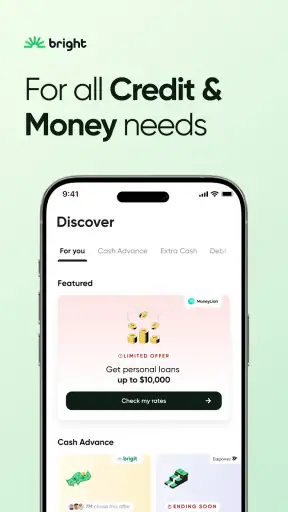
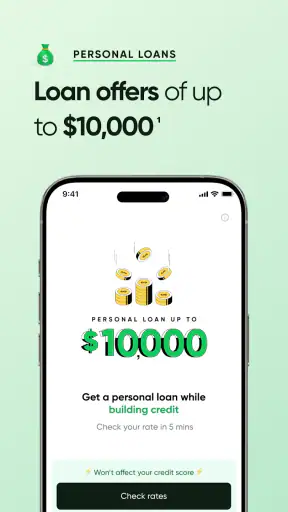
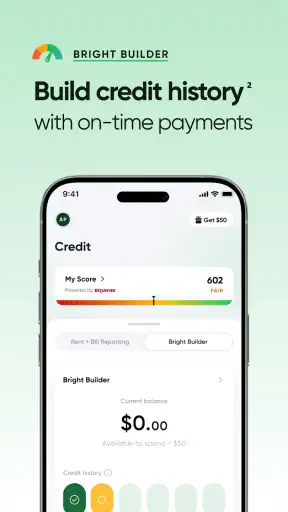
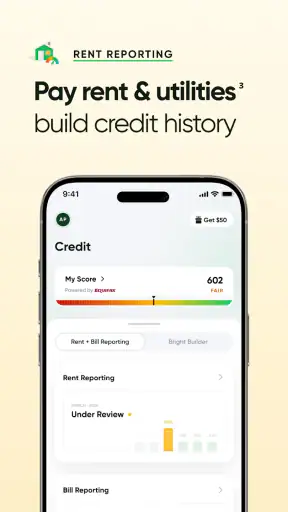
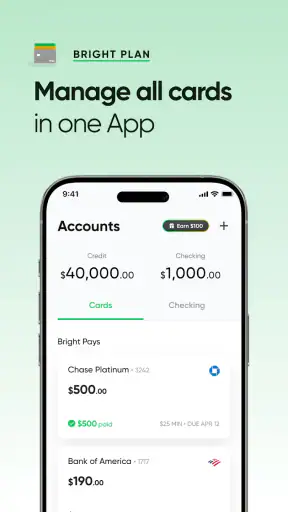
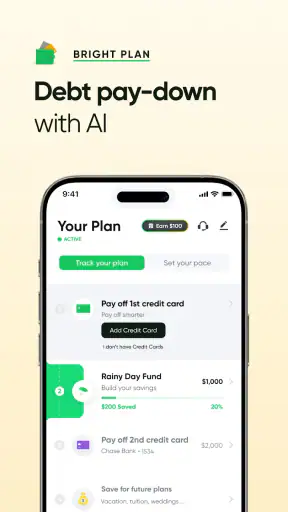
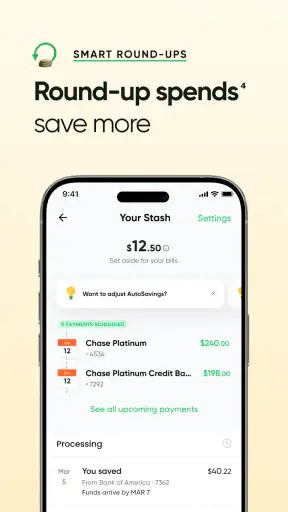
Bright: Loans & Credit Builder is the kind of finance app that makes a strong first impression because it brings several money concerns into one place. Instead of treating credit building, loan discovery, and credit-card access as completely separate tasks, it presents itself as a guided assistant for people trying to make sense of those choices. I found that approach useful during the first week, especially when I wanted a clearer next step rather than another page of general financial advice.
The bigger question, though, is whether it deserves a permanent place on your phone after the initial curiosity fades. My answer is qualified: it can be worthwhile for someone actively working on credit and willing to review financial suggestions carefully, but it is not a set-and-forget solution. Its lasting value depends on whether you have a real reason to check it regularly and whether you are comfortable making the final decisions yourself.
What the first week feels like
The app is developed by Bright Money and belongs to the finance category, with a free download and an Everyone age rating. Its central idea is easy to understand: use an AI-assisted experience to help you explore loans, credit cards, and ways to build your credit profile. That focus makes the opening experience more purposeful than a general budgeting app, because the questions it raises are tied to borrowing and credit access rather than everyday spending alone.
I would recommend approaching the first session with a specific goal. For example, you might be trying to understand why a credit application is difficult, preparing to compare borrowing options, or looking for a more disciplined way to improve your credit habits. Without a goal, the app can feel like a broad financial doorway: interesting, but not necessarily something you know how to use immediately.
The strongest early benefit is organization. Credit-related decisions are often scattered across lender websites, card applications, educational articles, and personal notes. A dedicated assistant can make the process feel less intimidating by giving the topic a single home. That does not remove the need to read terms or check eligibility, but it can reduce the friction of figuring out where to begin.
Bright has attracted a 4.6 average from roughly 165 thousand ratings and has passed one million installs, which suggests that the concept has reached a substantial audience. I see those figures as evidence of interest rather than proof that every recommendation will suit every user. Finance apps are highly personal: a tool that feels reassuring to someone rebuilding credit may feel unnecessary to a person who already has a simple, stable system.
One practical tip is to treat the first week as an information-gathering period, not an invitation to accept every financial offer. Write down what you are trying to improve before exploring the app. If your goal is a stronger credit history, separate that from the separate question of whether you actually need a loan or card. Those goals can overlap, but they should not automatically lead to the same product.
The app’s store summary positions it around an AI loan assistant, credit building, loans, and credit cards. In everyday use, that combination creates convenience, but it also creates a responsibility for the user. A recommendation can point you toward an option; it cannot decide whether the repayment schedule fits your income, whether a fee is acceptable, or whether borrowing is wise right now.
Useful for a real-life decision
Imagine someone receives an unexpected car-repair bill and has a limited credit history. They could open several lender pages, repeat the same information, and struggle to compare what appears on screen. Bright may provide a more approachable starting point by helping that person think through credit and borrowing in one workflow. The useful outcome is not simply finding an offer. It is recognizing the difference between an emergency solution and a new monthly obligation.
That distinction is where I think the app can offer more value than a basic credit-score checker. A score alone tells you a result. A guided finance experience can encourage you to connect the result with an action, such as reviewing repayment behavior, considering whether a card is appropriate, or delaying an application until your situation is clearer. The quality of that process still depends on your judgment, but the framing is helpful.
Why the value may continue from month to month
Credit building is rarely a one-session project. It usually requires consistent attention to repayment behavior, application choices, and the overall amount of debt being carried. That makes Bright more relevant to people who want an ongoing reminder of their credit-related priorities than to users who only want a quick answer today.
The recurring value comes from turning an abstract objective into a routine. I can imagine checking the app when reviewing monthly finances, before applying for a new credit product, or after a change in income. Those moments give the app a clear role. If none of them applies, its presence may gradually become background noise.
A useful monthly workflow is to review the app after paying regular bills, while the month’s financial picture is still fresh. Ask yourself three questions: has my borrowing need changed, am I taking on a payment I can comfortably maintain, and is the action I am considering meant to solve a short-term problem or build a longer-term record? This method prevents the app from becoming a button you press whenever a new offer appears.
Bright can also be useful as a comparison starting point. The usual alternative is to visit banks, card issuers, and loan providers one by one. That route may give you direct access to official terms, but it can be tiring and inconsistent because each provider presents information differently. A centralized assistant is easier for discovery, while direct provider pages remain better for confirming the final details before you commit.
That trade-off matters. Convenience is not the same as completeness. I would use Bright to narrow my questions and understand possible directions, then inspect the actual lender or card terms independently. Look closely at repayment amounts, fees, eligibility conditions, and what happens if your circumstances change. The app can help you get organized, but it should not replace the final reading of a financial agreement.
Another non-obvious benefit is that the app may help users slow down. When borrowing options are presented alongside credit-building goals, it becomes easier to notice that “getting approved” and “improving your finances” are not identical achievements. Someone may qualify for a product that still makes their monthly budget worse. The best long-term use is therefore reflective: use the assistant to clarify choices, not to turn every available offer into an action item.
Who is most likely to keep using it?
I see the strongest fit for people who are new to credit, rebuilding after financial difficulty, or trying to become more deliberate before applying for loans and cards. It may also suit users who dislike jumping between multiple financial websites and want a single place to revisit their credit-related plans.
It is less compelling for someone who already has a trusted bank relationship, understands credit products well, and checks their finances through a system that is working. That person may gain little from another app unless Bright offers a specific perspective they do not already have. Likewise, anyone looking for detailed expense categorization, investment research, or a broad household budget should consider a tool designed around those tasks instead.
The free price lowers the barrier to trying it, but “free” should not be confused with “risk-free.” The important cost may come from the financial decisions made after using the app. I would never install it with the assumption that an AI-guided recommendation automatically represents the cheapest or safest option for my situation.
The maintenance burden after the novelty fades
The main maintenance burden is mental rather than technical. A finance app only stays useful when you connect it to a repeatable habit. If you open it randomly, react to every suggestion, or check it only when you urgently need money, the experience can become fragmented. The app works better when you decide in advance what you want to monitor and how often you will review it.
I would keep a simple note outside the app containing my current goal, the monthly payment I can realistically manage, and the questions I still need answered. That small habit creates a useful boundary: Bright can help with discovery and guidance, while the note keeps the decision tied to my actual budget. It also makes it easier to notice when a new option does not match the original goal.
There is a second maintenance issue: financial circumstances change faster than a long-term plan. A new job, reduced hours, rent increase, or unexpected bill can make yesterday’s borrowing decision unsuitable today. Even if the app remains installed and its guidance is helpful, I would revisit the affordability question whenever my income or fixed expenses change.
Users should also expect to spend time interpreting rather than merely tapping. Credit language can be confusing, and a short explanation may not cover every detail that matters in a real agreement. If a recommendation seems attractive because it promises access or convenience, pause and ask what the total repayment could mean for your monthly cash flow. That extra step is essential, particularly for first-time borrowers.
The current version is 1.61.1 and supports devices running Android 8.0 or later. That makes it accessible to many Android users, including people who keep a phone for several years rather than upgrading frequently. Still, compatibility is only the starting point. The more important question is whether the app’s guidance remains relevant to your changing financial situation and whether you are willing to keep reviewing it instead of relying on an old plan.
Where fatigue can set in
The first source of fatigue is repetition. Credit improvement often involves patience, and no app can make responsible repayment feel instantly rewarding. If you expect a dramatic transformation after a few sessions, Bright may disappoint. Its role is better understood as a guide and organizer for ongoing decisions, not a shortcut around time and financial discipline.
The second is offer overload. Bringing loans and credit cards into the same experience can be convenient, but it may also tempt users to browse products when they do not need them. I would be especially cautious if I were already carrying balances or using credit to cover ordinary expenses. In that situation, the more valuable action may be reviewing the budget and reducing pressure, not exploring another application.
A third limitation is that personalization has boundaries. An AI assistant can make information feel more approachable, but it does not know every detail of your life unless you provide it, and even then it cannot predict every future expense. I would treat its suggestions as prompts for investigation. The moment a recommendation affects debt, repayment, or a new credit account, move from convenience mode into verification mode.
There is also a psychological trade-off. A polished, guided interface can make borrowing feel less serious than it is. That is not a flaw unique to this app, but it is worth recognizing here because loans and cards are central to the experience. I prefer using Bright when I am calm and comparing options, not when I am under pressure and looking for the fastest possible approval.
People who want a complete spending tracker may feel that the app’s focus is too narrow. A traditional budgeting app can be better for seeing groceries, subscriptions, utilities, and discretionary spending in one picture. A bank’s own app may be better for managing existing accounts. Bright makes more sense when the main problem is understanding credit access and borrowing choices, rather than monitoring every category of household spending.
My long-term verdict
Bright earns lasting space when it supports a deliberate credit habit, not when it becomes a shortcut to another application. I like its focused combination of credit-building guidance, loan exploration, and credit-card discovery, especially for users who feel lost among separate financial services. The free entry point makes experimentation easy, and its broad adoption shows that many people find this kind of assistant appealing.
My recommendation is to install it with a defined purpose. Use the first week to understand the guidance and identify the decisions that actually matter. During later months, return at a sensible interval tied to your budget review or a genuine credit need. Keep your affordability limits visible, compare final terms directly, and resist treating every available option as an opportunity you must take.
I would recommend it to a friend who is beginning to build credit, preparing for a serious borrowing decision, or wanting a more structured way to think about credit products. I would not recommend relying on it alone for a complete financial plan, nor would I suggest it to someone who is already comfortable with their current system and has no active credit-related goal.
Bright is best judged as a companion for better questions. It can help you ask what you are trying to accomplish, what a loan or card would change, and whether the proposed action belongs in your budget. It cannot replace careful reading, patience, or personal responsibility. Once that boundary is clear, the app has a reasonable chance of remaining useful after the novelty wears off.
For Android users, the combination of an Everyone rating, support for Android 8.0 and above, and a free download makes trying it straightforward. The real test comes afterward: if the app helps you make calmer, better-informed credit decisions month after month, it has earned its place. If it only encourages occasional browsing without improving your habits, removing it may be the more financially sensible choice.


